IN THE alphabet soup of modern investing, the G in ESG can be the easiest letter to overlook.
Governance happens mostly away from public view – in boardrooms, internal controls, ownership records and disclosure reports. It determines who makes corporate decisions, who watches them and how those in power are held accountable.
Yet it may also be the pillar upon which investor confidence ultimately rests.
At its core, the governance pillar of environmental, social and governance or ESG, concerns how a company is directed and controlled.
It encompasses board independence, accountability, business ethics, risk management, transparency and safeguards against conflicts of interest.
Without these, environmental promises and social commitments risk becoming little more than words on glossy sustainability reports.
In the Philippines, regulators are putting more weight behind that principle.
At the centre is the Securities and Exchange Commission (SEC), which has rolled out reforms aimed at tightening corporate oversight while trying to build a deeper and more competitive capital market.
The Philippine Stock Exchange (PSE), meanwhile, occupies a unique place in that system. It is itself publicly listed, but also serves as the country’s only stock exchange and a self-regulatory organisation overseeing listed firms’ compliance with listing and disclosure rules.
Together, the two institutions form much of the machinery through which corporate governance moves from principle to practice.
Putting independence to the test
One of the clearest examples is the SEC’s decision to draw harder lines around how long directors can stay.
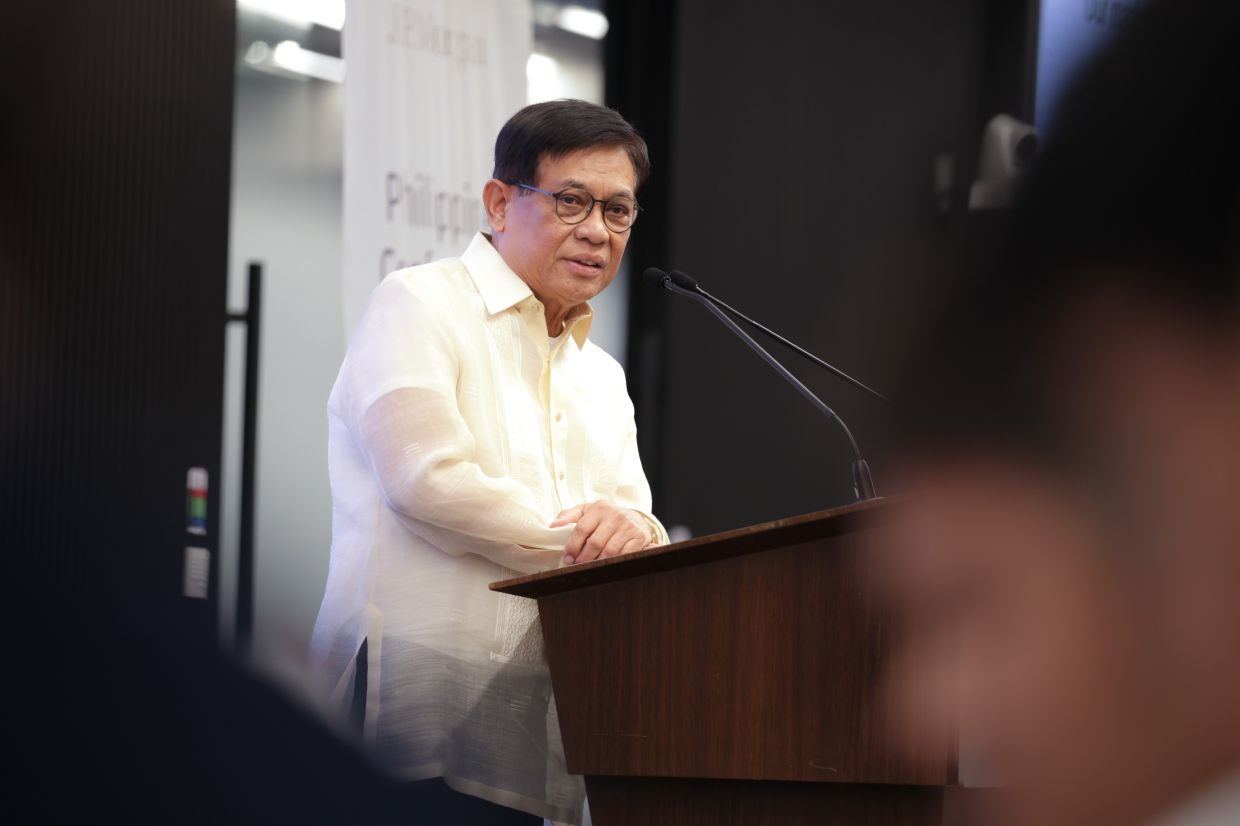
Under Memorandum Circular No. 7, series of 2026, the regulator imposed a strict nine-year cumulative term limit for independent directors of publicly listed companies.
“A strict term limit ensures that independent directors maintain the objectivity and impartiality required to serve the very purpose envisioned under the law,” SEC chair Francis Lim said when the rules were announced.
The SEC later extended the governance push to the exchange itself. Memorandum Circular No. 17 imposed a cumulative 10-year term limit on broker directors of exchanges to encourage greater diversity, independence and professional expertise.
The move proved contentious, with longtime PSE broker directors challenging the restriction.
Lim, however, had earlier made the SEC’s position clear.
“As far as I am concerned, term limits are non-negotiable,” he told reporters in March, while saying the regulator remained open to valid comments from the market.
The dispute brought a larger governance question to the fore: when does longevity in the boardroom begin to compromise independence?
For the SEC, independence cannot simply be a title. The structures protecting it matter, too.
Beyond the boardroom
Board tenure is only one part of the government’s governance push. The SEC has also launched Harbor, a web-based registry for beneficial ownership disclosures aimed at strengthening corporate transparency and supporting the country’s anti-money laundering and counterterrorism financing commitments.
It is likewise reviewing rules that could designate private corporations receiving government contracts above specified thresholds as corporations vested with public interest.
The proposal brings corporate governance directly into the use of taxpayers’ money. The SEC said it is intended to safeguard public funds and help fight corruption.
The regulator is also proposing tighter accreditation requirements for auditing firms and external auditors, including those handling companies with significant government infrastructure contracts, to improve audit quality and confidence in corporate disclosures.
Taken together, the measures broaden governance beyond how management answers to shareholders. They ask whether ownership can be traced, corporate information can be trusted and businesses dealing with public money face sufficient scrutiny.
Training the people in charge
The SEC is also tightening oversight over the people expected to make those systems work.
Under Memorandum Circular No. 25, series of 2026, board members and key officers of covered entities must undergo corporate governance training at least once every calendar year.
For first-time directors and key executives, required topics include board responsibilities, protection of minority interests, financial oversight and audit, compliance and ethics, conflicts of interest, related-party transactions and director liabilities, among others.
More importantly, the SEC is putting controls around the training itself. It regulates training providers, requires documentation and may send representatives to observe and monitor programmes.
In other words, the regulator is not merely telling corporate leaders to understand good governance. It wants a way to check that they do.
Watching the market – and the watchdog
The PSE adds another layer to this governance structure. As a self-regulatory organisation, it monitors listed companies’ compliance with listing and disclosure requirements.
Yet because the PSE is itself a listed corporation, it too operates within the SEC’s regulatory reach.
The result is a chain of accountability: corporate managers answer to boards, listed companies answer to investors and exchange rules, the PSE exercises regulatory functions over listed firms and the SEC oversees corporations and market institutions.
The broker-director controversy underscores why that relationship matters: Even the institution policing listed companies must itself be governed.
That becomes even more important as the SEC tries to attract more capital into the country.
The regulator is working with the World Bank to overhaul the public offering framework and with the PSE and Philippine Dealing and Exchange Corp on market-making rules.
It is also developing a Philippine Capital Market Master Plan with the Asian Development Bank as part of its goal of positioning the country among South-East Asia’s leading capital markets by 2030.
“We have made progress in reducing regulatory friction, but there are still structural barriers that prevent businesses from starting faster and companies from tapping the capital market more efficiently,” Lim said in August.
“Our next task is to address these barriers and build a market that is easier to access, more liquid and more competitive,” he added.
But opening the doors wider to companies and investors carries another requirement: convincing them that the institutions behind those doors can be trusted.
Amid corruption concerns last year, Lim warned: “When trust breaks down, capital dries up and everyone – government, business, and the public – pays the price.”
That may ultimately explain why governance reforms matter beyond board composition, training requirements or ownership registries.
A capital market depends not only on companies willing to raise money and investors willing to provide it.
It also rests on confidence that directors can exercise independent judgment, ownership can be traced, disclosures can be trusted and rules can be enforced.
In that sense, governance is more than the G attached to ESG. It is part of the infrastructure on which the market runs.
And as the Philippines tries to build a bigger and more competitive capital market, the real measure of its governance push will not be how many rules regulators can write.
It will be whether investors trust the institutions those rules are meant to govern.