IN an uncertain and ever-changing financial landscape, the desire to protect one’s investments against market volatility is often instinctive.
For some, the immediate response is to sell, move into cash and wait for conditions to improve. Undoubtedly, it sounds like a safe and sensible precaution, particularly when economic uncertainty dominates the headlines.
However, deciding when to return to the market is rarely a straightforward matter. If prices continue to fall, some will likely hesitate for fear of further losses. When markets recover, there could be a notion of missed opportunity resulting in a pause for another possible correction. This dilemma may ultimately leave some investors on the sidelines for an unforeseeable amount of time.
For nearly two decades, Areca Capital has witnessed changing attitudes towards wealth and investing across different market cycles.
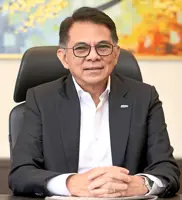
According to its chief executive officer, Danny Wong, conversations that once centred largely on investment returns and wealth accumulation have evolved to encompass retirement planning, wealth preservation and succession.
Yet one recurring challenge remains and that is how investors perceive and respond to risk. “Many people equate risk with market volatility. When markets fall, they immediately think risk has increased. When markets are rising, they feel safer,” Wong observes.
The problem, Wong believes, is that investors often concentrate on the risks they can see while overlooking those that develop gradually. Inflation, excessive cash holdings, poor investment decisions and procrastination can be just as damaging to long-term wealth as a market downturn.
The cost of waiting
Unlike a sudden fall in share prices, inflation rarely causes immediate alarm. Its effects are gradual and often go unnoticed, particularly among investors holding substantial cash reserves. While their savings may appear secure, rising living costs can diminish their purchasing power, especially if the interest earned fails to keep pace with inflation.
Wong is quick to point out that holding cash is not inherently a poor decision.
“Cash is important,” he stresses. “It gives flexibility and peace of mind. But cash is not meant to stay idle forever.”
The difficulty arises when investors retain more cash than they need while waiting for the ideal moment to invest.
Wong has encountered investors who remain cautious during market declines, expecting prices to fall further, only to hesitate again when a recovery begins. Some repeat this cycle for years, missing opportunities while their cash gradually loses purchasing power.
“Sometimes the risk is not losing money. It is failing to grow it,” he explains.
The question though is not whether investors should hold cash, but whether the amount retained is appropriate for their needs. A clear delineation must be set and that is funds set aside for short-term expenses serve a different purpose from those intended for retirement or future generations.
Knowing when to act, and when not to
Investor behaviour is another concern, particularly when financial information is available almost instantly, practically at their fingertips.
Wong recalls that two decades ago, investors had considerably less access to market information. Today, they face a continuous stream of economic forecasts, commentary and investment opinions.
“More information does not always lead to better decisions,” he cautions. During periods of uncertainty, investors may sell after markets have already fallen, only to return when prices recover. Although moving into cash offers immediate reassurance, buying back at higher prices may leave them worse off.
Wong advocates measured portfolio adjustments rather than repeatedly changing investment strategies in response to short-term developments. “A sound investment plan should not change every few months simply because market sentiment does,” he says.
It is a philosophy that echoes Warren Buffett’s observation in Berkshire Hathaway’s 1987 shareholder letter: “Mr. Market is there to serve you, not to guide you.” Market fluctuations can present opportunities, but they should not dictate every investment decision.
A clear strategy allows investors to assess changing conditions without being swayed by prevailing sentiment.
Equally important is understanding the purpose of each investment within a portfolio. Wong likens this scenario to that of a football team, where defenders and forwards have different responsibilities. Judging a defender solely by goals scored would make little sense.
Similarly, an investment intended to provide stability should not be assessed by the same expectations as one selected for growth. Each plays a different role within the portfolio. For investors with the time, knowledge and experience to manage their own investments, active involvement may be appropriate while others may benefit from licensed professionals.
“There are different roles involved.
“As investment advisers, we look at the client’s overall portfolio, objectives and asset allocation.
“As fund managers, it is our job to manage the underlying investments: researching opportunities, monitoring markets and risks, and making tactical adjustments when necessary. So sometimes the adviser’s role is also to help clients stay disciplined and avoid unnecessary changes. But staying invested does not mean doing nothing,” Wong explains.
Building wealth, trust and legacy across generations
Over the years, Wong has seen a change in what clients expect from wealth management. Twenty years ago conversations largely revolved around investment returns and accumulating assets.
Today, many of those same clients are approaching retirement, supporting grown-up children or considering how their wealth will pass to the next generation.
To address these evolving needs, Areca Capital Group also offers wealth succession planning services through Areca Capital Trustees Bhd, its corporate trustee entity.
Some of Areca Capital’s relationships now extend across three or four generations of the same family, reinforcing Wong’s belief that managing wealth requires understanding what money is intended to achieve.
He offers an example of a grandfather who has secured sufficient funds for retirement. While his living expenses may warrant a conservative investment approach, another portion intended for his grandchildren could remain invested for another decade or two.
That money may accommodate greater investment risk because it serves a different purpose.
“The appropriate level of risk depends not only on the investor’s age, but also on the purpose and time horizon of that specific pool of money,” Wong elaborates.
Risk also changes depending on what the money is meant to achieve.
For instance, money required for retirement next year should not necessarily be managed the same way as wealth intended for grandchildren 15 or 20 years from now.
This approach reflects Areca Capital’s work across investment management, financial planning and private wealth advisory, where understanding clients’ family circumstances and future obligations is as important as assessing their portfolios.
Estate planning also forms part of that discussion, particularly when wealth is intended for future generations.
For Wong, managing risk comes down to understanding the consequences of both action and inaction. “There is risk in investing, and there is also risk in not investing. There is risk in acting, and there is risk in waiting indefinitely.”
A market downturn may be unsettling, but it need not derail a carefully considered investment strategy.
What deserves equal attention is whether the decisions made to avoid short-term losses could create greater financial difficulties in the years ahead.
Ultimately, much depends on the ability to make sound decisions without allowing emotions to dictate the outcome.
It is a principle Warren Buffett articulated in his preface to Benjamin Graham’s The Intelligent Investor. “To invest successfully over a lifetime does not require a stratospheric IQ, unusual business insights, or inside information. What’s needed is a sound intellectual framework for making decisions and the ability to keep emotions from corroding that framework.”
Disclaimer:
This article is provided for general informational and educational purposes only and does not constitute, and should not be construed as, professional financial, legal, tax or investment advice.
Any views, examples or references contained herein are generic in nature and do not take into account the specific investment objectives, financial situation, risk tolerance or particular needs of any individual.
Readers are strongly encouraged to seek independent advice from qualified professionals before making any financial or investment decisions.
While the information contained in this article is derived from sources believed to be reliable as at the date of publication, Areca does not make any representation or warranty, express or implied, as to its accuracy, completeness or reliability.
No reliance should be placed on the information provided and Areca disclaims all liability in respect of any losses or outcomes arising from the use of or reliance upon this article.