Sime Darby Bhd calls itself a dividend stock. With a trailing dividend yield of some 5.88%, the group is also aiming for bottom-line growth, targeting considerably higher earnings by financial year 2029 (FY29), ending June 30.
Its three-year plan, highlighted in its 2026 annual report, aims for RM2bil in core net profit, a 10% return on shareholders’ equity and RM20bil in market capitalisation by FY29.
This would require the group to add about RM453mil to its FY26 core net profit over three years and grow its market value by about a quarter from roughly RM16.36bil, assuming a fixed share price.
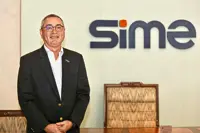
Sime Darby’s chief executive officer Datuk Jeffri Salim Davidson appears to be up for the challenge. He believes several factors will work in the company’s favour in the near to medium term, supporting those targets.
In FY26, the group declared a dividend of 14 sen a share, amounting to RM954mil, or 62% of core net profit.
Its policy is to distribute at least half of its core earnings. The question is whether its various business segments can generate the profits and cash needed to grow while maintaining those payments.
One avenue for growth is the service work that follows an equipment sale: parts, repairs and maintenance that can provide recurring income for the group.
The industrial segment, Sime Darby’s biggest profit contributor, illustrates both the opportunity and the uncertainty.
Its core profit before interest and tax (PBIT) fell from RM1.31bil in FY25 to RM1.25bil in FY26, a 4.3% decline, largely because Australian miners delayed equipment servicing and rental demand weakened.
Jeffri says miners had held back scheduled repairs and rebuilds for roughly two years as costs rose and uncertainty made them cautious.
“What’s happened is they’ve been holding back, but over the last couple of months, we’re seeing it now, they finally cannot hold back any more.
“They’re coming back, so we’re seeing our parts and service business, certainly over the last few months, beginning to come back,” he tells StarBiz 7.
He believes the postponed work has created a backlog that he expects will eventually drive a recovery.
“It’s all recurring income. High margins. These have good margins. Our parts margin is generally north of 20%-25%, while our service business is sometimes north of 50%. So, you know, if you add it up, then you’re talking about pretty solid profits,” Jeffri says.
Those are the margins Jeffri associates with such recurring activities.
In Australasia, Sime Darby’s equipment order book stands at RM1.5bil, largely driven by mining customers capitalising on strong commodities demand and requirements from data centres.
Data centres also offer a less obvious source of recurring income for Sime Darby.
These facilities buy Caterpillar standby generators to keep operating if the power grid fails, with delivery potentially followed by years of servicing, given the reliability demanded of backup power systems.
Jeffri says Sime Darby supplies Caterpillar generators to data centres in Malaysia, China, Australia and New Zealand, among other markets.
“Because Caterpillar is reliable, these are standby (generators), so what I mean by reliable is that when there’s an electricity failure, they’ve got to come on.
“After we sell them, because they need to be so reliable, customers normally enter into 10-year or five-year agreements, depending on their requirements, for us to maintain the data centres,” Jeffri says.
“So that’s also more revenue for us, recurrent revenue at high margins. That’s why it’s good for the long term.”
Sime Darby’s FY26 annual report notes that Malaysia’s order book is supported by multiple power systems and energy services projects for data centre infrastructure, as well as industrial engines.
Its order book in China has, meanwhile, doubled, supported by the stronger demand for power systems and data centre projects.
Jeffri says Sime Darby currently has a robust equipment order book of more than RM4.66bil across its business footprint.
His remarks on data centre projects run counter to the popular view that the group’s exposure ends once a generator is delivered to a data centre.
A different test of its FY29 ambitions lies in mainland China, once a substantial source of profit for its motors division. Luxury car demand has weakened there, while domestic manufacturers have grown stronger and put pressure on established foreign brands.
“They’re producing good cars at a pretty good price point. And this has been changing the market share (structure) there,” Jeffri says of Chinese automakers.
“And we are also affected. So we have been losing money in China for the last two, three years – probably about 10 quarters (in all). We’ve done quite a lot there, and it’s been very tough in China.”
The group’s response has been to close under-performing dealerships, cut overheads and focus solely on BMW.
Jeffri says Sime Darby exited its other established foreign franchises there, including Volvo, Hyundai and Kia, while continuing to assess opportunities with Chinese brands.
“So we’ve downsized, we’ve cut our branches, we’ve cut our staff size in China. It’s shrunk from almost 2,500 to 1,500,” he says.
“We are still losing, but it’s on a breakeven-ish (basis) now. We lost a little bit of money last year. But we’re going to break even this (financial) year,” he adds.
The group’s annual report states that it made RM38mil in core PBIT for the wider China Motors region, indicating improved performance in Hong Kong, Macau and Taiwan, alongside its mainland China operations.
Jeffri expects BMW’s new Neue Klasse range, developed with technology tailored to China, to help the brand compete in the country’s increasingly competitive market.
The first model, the iX3, was launched there in August and has received strong customer and market acclaim, he says.
“We’ve taken quite a lot of orders, so we shall see. It’s using Chinese technology.
“They’re embracing Chinese technology and getting pretty nice cars with all the technology and interface you’d expect from a Chinese car. And they’re coming in at an affordable-ish price,” Jeffri says.
The performance of this new vehicle line amid intense competitive will help determine whether Sime Darby’s turnaround in China holds.
“We’re going to stick with BMW because we believe that BMW has got a fighting chance in China. There is still a market for luxury cars in China, no matter what people may say,” he says.
“The BMW network in China will shrink. The big dealers will phase out. But I think Sime Darby, as a strong dealer, will remain there and become one of the bigger dealers among the potentially fewer, bigger dealers in China moving forward,” Jeffri adds.
In Australia, Sime Darby sees a longer-term equipment opportunity in copper.
Its RM1.5bil acquisition of Cavpower in 2023 gave it the Caterpillar dealership in South Australia, where BHP is developing its copper operations.
Jeffri sees demand initially coming from infrastructure construction, followed eventually by fleets serving expanded mines.
“At the moment it’s still small,” he says of the copper opportunity.
Mining developments require roads, rail and water supply, according to Jeffri. That work may itself require Caterpillar machines before new mining fleets are ordered.
“So all of that is being built, which means that at some point, you know, there will be mega fleets that we will sell to them. And CAT is BHP’s preferred partner.
“So that is a big opportunity to come.
“When will it come? I think it will be in stages, so it will build up over time. And of course, don’t forget, we also participate in the infrastructure world.
“We also know that copper is going to be more and more in demand due to the energy transition that’s happening,” he adds.
Copper’s superior electrical and thermal conductivity compared with most other metals makes it highly efficient at transferring power with minimal energy loss.
At home, Sime Darby’s exposure to Malaysian vehicle buyers provides another pillar of earnings.
Through Toyota and its interest in Perodua, Sime Darby’s combined market share was 53.7% of Malaysia’s vehicle market in FY26, according to its annual report.
UMW, which houses much of that exposure, generated RM15.8bil in revenue and RM945mil in PBIT in FY26.
Both UMW’s top and bottom lines were lower than in the preceding year as its automotive subsidiaries sold fewer vehicles, although higher contributions from associates and lubricants softened the profit decline.
Jeffri says Sime Darby is positioned to sell internal combustion engine vehicles, hybrids and electric vehicles (EVs) as customers’ preferences change.
Its Inokom plant in Kulim, Kedah, was named BYD’s local assembly partner in mid-October.
He expects EV adoption in Malaysia to continue growing, but says subsidised petrol and charging infrastructure will moderate the pace.
“And the infrastructure is not quite developed yet. So if you drive your EV to Alor Setar, for example, it’s a problem. You don’t know if there are adequate (working) chargers around.”
There is also a sizeable base of buyers seeking cars priced below RM100,000.
“The national segment, the Perodua plus Proton segment: the under-RM100,000 segment is very resilient,” he says.
For 2026, Jeffri expects Malaysian industry sales of around 800,000 vehicles, near last year’s level.
He suspects sales could ease in 2027, though he acknowledges that the market has repeatedly proven to be more durable than he expected.
“Look, I get this wrong every year.
“I always think the Malaysian auto sector should shrink as it is too big,” he says.
“It should come down, but I’ll (probably) get it wrong again. It’s steady. It seems to be a steady market now.”
The breadth of Sime Darby’s businesses has helped it absorb weakness in its China motors segment over the past two to three years.
The group says its FY26 core net profit rose 32.6% year-on-year (y-o-y) to RM1.55bil, even as industrial earnings eased and its mainland China motors segment remained in the red.
Reported net profit, however, fell 14.5% y-o-y to RM1.76bil as disposal gains declined and impairments weighed on results.
For a group seeking to maintain strong dividend payouts while growing profits, the test now is whether early improvements in Australian servicing, data centre maintenance and its China motors business approaching breakeven can translate into a sustained earnings rebound.
Already a subscriber? Log in
Get 20% OFF The Star Digital Access
Cancel anytime. Ad-free. Unlimited access with perks.