PETALING JAYA: Johor Plantations Group Bhd (JPG) is expected to benefit from a tighter crude palm oil (CPO) supply outlook, with stronger realised prices potentially supporting margins and earnings into financial year 2027 (FY27).
Its downstream expansion is also set to become increasingly important, as the Integrated Sustainable Palm Oil Complex (iSPOC) in Sedili, Johor, is expected to add a new earnings stream from FY27.
Apex Securities Research initiated coverage on JPG with a “buy” recommendation and a target price of RM2.23, based on a sector peer average FY27 forward price-to-earnings multiple of 15.1 times applied to its FY27 forecast core earnings per share (EPS) of 14.7 sen.
This is supported by a three-star environmental, social and governance rating.
The research house said JPG’s predominantly upstream earnings exposure should allow it to benefit from higher CPO prices, particularly as plantation costs are not expected to rise proportionately with selling prices.
“The key catalyst would be downward revisions to Malaysian and Indonesian production expectations as El Nino develops, potentially extending the current high-CPO-price environment into FY27,” Apex Research said.
The brokerage also highlighted iSPOC as a key longer-term earnings driver. The facility represents JPG’s move beyond bulk CPO and palm kernel (PK) production towards higher-value palm-based products.
“We believe that a successful commissioning and utilisation ramp-up could meaningfully lift earnings from FY27 and potentially support a higher valuation multiple as the earnings mix shifts toward value-added downstream products,” it said.
Phillip Capital Research, meanwhile, raised its 2026-28 estimated EPS forecasts by 1%-13% to reflect higher PK price assumptions, despite lowering its fresh fruit bunches (FFB), CPO and PK production assumptions.
The brokerage raised its 12-month target price for JPG to RM1.97 from RM1.75, based on an unchanged 15 times 2027 estimated EPS, while maintaining a “hold” recommendation. JPG closed 0.52% lower at RM1.50 last Friday.
The research house expects JPG to record a stronger second half of 2026 (2H26), driven by seasonal crop recovery, improving operating leverage and sustained external crop sourcing.
“iSPOC should add a new earnings stream from FY27 and enhance earnings diversification,” it said.
However, the brokerage believes it remains premature to ascribe a significant valuation re-rating to the project as its earnings contribution builds progressively following commissioning.
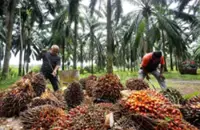
On plantations, the research house expects FFB production to recover progressively in 2H26 as harvesting conditions improve.
“Higher internal production, alongside sustained external crop sourcing, should support better mill utilisation, fixed-cost absorption and margins,” it said.
However, the recovery is expected to remain gradual as replanting and weather risks continue to weigh on near-term output.
Phillip Capital Research consequently trimmed its FY26-FY28 FFB production forecasts by 1%-5%, while expecting growth to strengthen from FY27.