PHNOM PENH: Cambodia has introduced new financial reporting rules that could ease mandatory audit requirements for many small and medium-sized enterprises (SMEs), while expanding oversight of foreign company branches, casino operators and large property developers, according to legal and tax specialists.
The changes, introduced under Prakas 063, signed on August 18, 2026, revise the financial thresholds that determine which businesses must undergo independent audits, while establishing new requirements for certain sectors and non-governmental organisations (NGOs).
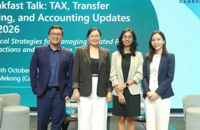
The reforms were highlighted during a tax and accounting briefing organised by the European Chamber of Commerce in Cambodia (EuroCham) and legal and tax advisory firm DFDL at the Novotel Phnom Penh on October 6.
“The new regulation represents a significant change in Cambodia’s financial reporting framework, particularly in determining which businesses must prepare and submit independently audited financial statements,” said DFDL accounting director Michelle Cielo.
Under the revised rules, the turnover and asset thresholds triggering mandatory audits have been raised, with different criteria introduced for specific sectors for the first time.
The changes mean that many small and medium-sized businesses previously subject to compulsory audits may no longer be required to undergo the same process, potentially reducing their accounting and compliance costs.
However, the revised framework also expands audit requirements to several categories of businesses, including branches of foreign companies, casino operators and large property developers, regardless of certain financial thresholds.
NGOs will also face specific requirements based on project costs or a combination of overall expenditure and staffing levels.
“Businesses and NGOs falling outside the new thresholds may apply for exemptions, but applications must be submitted within 30 days of the end of their accounting year,” Cielo explained.
She also highlighted stricter penalties for late filing and non-compliance, noting that unpaid penalties could double after 30 days and triple after 60 days, with further enforcement measures possible.
The briefing did not specify the revised turnover and asset thresholds or the number of businesses expected to benefit from the changes.
The accounting reforms come as Cambodia continues to strengthen tax administration and scrutiny of corporate financial transactions, particularly those involving related companies and cross-border business arrangements.
DFDL tax partner Vajiravann Chamnan outlined several regulatory developments affecting businesses in 2026, including the introduction of a 20 per cent capital gains tax on taxable gains from specified capital assets.
These include share transfers, investment assets, goodwill and intellectual property, although implementation timelines differ depending on the asset category.
“Generally, applicable capital gains tax declarations must be submitted within three months of the relevant transaction,” said Chamnan.
She explained that the new provisions clarify the responsibility for outstanding tax liabilities when businesses are sold, merged or undergo share transfers.
The rules are intended to establish which entities remain responsible for unpaid taxes following corporate restructuring, including situations in which businesses have not properly completed deregistration procedures.
Chamnan noted that transactions between related companies remain a major focus of scrutiny by the General Department of Taxation (GDT).
These include intercompany loans, management fees, sales of goods and royalty or licensing payments.
Where tax authorities determine that transactions have not been properly documented or justified, businesses may face the disallowance of related-party expenses, additional tax assessments and penalties ranging from 10 to 40 per cent, together with monthly interest.
More serious cases involving deliberate tax evasion or fraud may result in additional enforcement measures.
DFDL transfer pricing specialist Vandana Vijayakumar highlighted changes under Prakas 574, which governs transactions between related parties.
She explained that adjustments made by tax authorities to the prices charged between related companies could result in further tax consequences if the difference is subsequently treated as a dividend, loan or capital contribution.
The regulation also provides two separate exemption mechanisms, including relief from full transfer pricing documentation requirements for qualifying businesses based on financial thresholds and a narrower exemption applying to certain related-party loans.
Vijayakumar stressed that businesses must reassess their eligibility for these exemptions annually rather than assume that previous qualifications remain valid.
She advised companies to document all related-party transactions, regularly review applicable exemptions and maintain evidence demonstrating that their transactions comply with the arm’s length principle, under which related companies should transact on terms comparable to those agreed between independent businesses.
During a question-and-answer session moderated by DFDL tax partner Diberjohn Balinas, participants raised concerns about the tax treatment of loans and cash advances between parent companies, shareholders and related entities.
Questions also focused on determining appropriate interest rates for intercompany financing and understanding how the revised accounting requirements would affect businesses newly subject to mandatory audits.
The discussions reflected practical concerns among companies navigating Cambodia’s evolving regulatory framework, particularly those involved in cross-border transactions or operating through complex corporate structures.
While the revised audit thresholds could reduce compliance obligations for some smaller enterprises, the expanded requirements for particular sectors and increased scrutiny of related-party transactions mean businesses will need to review their financial reporting and tax practices carefully.
The changes also place greater importance on understanding which obligations apply to individual businesses, as companies prepare their year-end financial statements and assess their compliance requirements for 2026. - The Phnom Penh Post/ANN