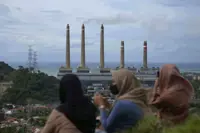
PETALING JAYA: Kinergy Advancement Bhd ’s proposed RM80mil private placement is seen by analysts as a timely funding move that supports the group’s expansion into power generation, particularly its planned 1,500-megawatt (MW) gas-fired power plant in Perlis.
RHB Research said the exercise provides investors with an opportunity to participate in the group’s potential upside from the new power plant. Part of the proceeds will also go to reduce borrowings.
“We view this as a good opportunity to ride Kinergy’s upside from the new power plant, as we expect management to sign the power purchase agreement in the first quarter of 2027. Kinergy is proposing to undertake a private placement of 219 million shares, making up 10% of its current share capital.
Based on an indicative issue price of 36.5 sen, which was a 13% discount to the current stock price, the group is expecting to raise up to RM80mil from the exercise.
The company intends to allocate RM49mil, or 62% of the proceeds, to fund its Perlis gas plant and the balance to repay bank borrowings.
RHB Research said the proposed private placement may be implemented in tranches within the next six months from the time of the regulator’s approval and is expected to reduce the group’s net gearing from 0.9 times to 0.6 times.
Assuming it holds a 20% stake in the new power plant facility, the research house estimates that Kinergy will need to inject RM180mil in equity for the project’s Phase 1.
It forecast a RM9bil capital expenditure for the 1,500MW gas plant with 80% debt funding. The remainder of the equity portion for this project will be funded by internal cash, according to management.
The group had already appointed a main contractor to begin ground works at site as it expects to take delivery of the first turbine in the first half of 2027. Phase 1 (750MW) is targeted for commissioning by December 2028.
“Upon full commissioning, we estimate the plant will contribute RM78mil to Kinergy based on its 20% stake.
“We also expect it to recognise RM400mil in construction revenue from Phase 1 of the project,” said RHB Research, which kept a “buy” call with a 60 sen target price.
Meanwhile, Apex Research also maintained a “buy” rating and had a 67 sen target price on the stock.
This is based on 22.7 times financial year 2028 earnings per share of 2.94 sen.
“The proposal adds about 10% to the share base and is not yet in our forecasts. We will reassess the enlarged share base and earnings impact upon completion,” Apex Research said in a note to clients.
It noted that the RM49.4mil earmarked from the proceeds is only the first instalment. The brownfield project’s total cost is approximately RM4.7bil, which will be funded 80% by debt and 20% by equity.