PETALING JAYA: Plantation companies are expected to benefit from stronger realised crude palm oil (CPO) prices in the third quarter of financial year 2026 (3Q26), though the upside may be tempered by lower-than-expected CPO production and sticky production costs, according to MBSB Research.
The research house said it expects 3Q26 earnings across companies in its coverage to largely track expectations, even as Sarawak Plantation Bhd , Johor Plantations Group Bhd and TSH Resources Bhd see weaker year-on-year (y-o-y) output for fresh fruit bunches (FFB) and CPO.
It noted that CPO prices averaged RM4,552 per tonne during the quarter, up 0.7% quarter-on-quarter (q-o-q) and 6.6% y-o-y, which is likely to help offset the impact of softer production among these companies.
“Overall, however, wider CPO output was generally ‘decent’ across the sector,” MBSB Research said.
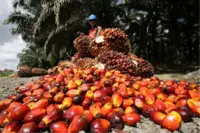
The Malaysian Palm Oil Board (MPOB) reported CPO production jumping to 5.7 million tonnes, increasing by 19.7% q-o-q and 4.0% y-o-y, in line with higher FFB receipts.
“Within our coverage, Johor Plantations recorded weaker output (minus 10.8% y-o-y, minus 3.7% year-to-date), partly reflecting a disproportioned prime age profile due to high replanting rate carried into the quarter,” the research house noted.
According to MPOB, FFB production was higher at 29.1 million tonnes, marking a rise of 20.6% q-o-q and 2.6% y-o-y.
“Production across our coverage has generally held up better at about 9.9% y-o-y, likely supported by stronger Indonesian output among the integrated players,” MBSB Research said.
This would bring FFB output growth for the first nine months of 2026 to 4.1% year-to-date, following a weak start in 1Q26, it said.
Meanwhile, the research house noted that upstream margins could stay under pressure as fertiliser prices, while moderating, remain above 3Q25 levels.
“Industry’s cost of production is likely to remain sticky at RM2,500 to RM2,600 per tonne, driven by continuation of elevated fertiliser prices, unless planters delay application,” it said.
In terms of downstream players, it said that while elevated freight and insurance costs amid tensions in the Strait of Hormuz continue to place pressure on companies, margins are expected to be steady given the uptick in palm kernel prices.
MBSB Research has maintained its “neutral” position on the sector, as well as its 2026 CPO price assumption of RM4,400 per tonne.
The research house highlighted SD Guthrie Bhd as a “buy” pick with a target price of RM7.65.
It cited a Malaysia production growth of around 5%, underpinned by a strong 19.63 tonnes per hectare FFB yield and oil extraction rate of 21.3%, as well as a recurring RM500mil to RM700mil per annum from land monetisation activities.