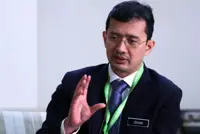
KUALA LUMPUR: Malaysia's fiscal deficit target of 3.3% of gross domestic product (GDP) for 2027, below market expectations of 3.5%, depends largely on nominal GDP growth rather than spending cuts, according to Moomoo Malaysia strategist Yu Junqiang.
Yu said net fiscal consolidation amounted to RM1bil, with much of the improvement in the deficit ratio expected to come from economic growth.
He said the fiscal outlook also hinged on a RM40bil ceiling on fuel subsidies and revenue projections that had yet to account for income tax cuts announced under Budget 2027.
Keeping fuel subsidies within the allocation would depend on global crude oil prices and the pace of subsidy rationalisation.
Yu was selectively positive on equities, particularly sectors benefiting from specific government allocations.
“Construction stands out, with RM3.3bil allocated to East Malaysia and RM2.3bil to rural roads. Water infrastructure benefits from RM2.5bil directed at non-revenue water, and utilities and telcos are also well positioned,” he said.
However, he expected the budget's direct impact on the broader equity market to remain limited.
On Malaysian Government Securities (MGS), Yu maintained a slightly positive outlook, citing lower gross bond supply and a projected decline in government debt to 63.7% of GDP in 2027.
“The key indicator to monitor is auction cover on the upcoming 10-year and 30-year papers, measured against a relatively soft 2.01x baseline. Stronger cover would point to growing investor confidence in the fiscal path,” he said.
Meanwhile, the ringgit was expected to remain largely driven by external factors, particularly US Federal Reserve policy and global crude oil prices.
Yu identified banks and small and medium enterprises (SMEs) as among the main beneficiaries of the budget.
He said the absence of a windfall tax removed a key risk for banks, while RM20bil in SJKP housing credit guarantees and RM11.6bil in SME and microfinance facilities would support lending.
The 14% cap on credit card annual percentage rates could affect unsecured lending, although the impact was expected to be contained.
About 300,000 SMEs would benefit from a one percentage point tax cut, while the extension of Accelerated Capital Allowance until 2030 would support capital expenditure.
Businesses could also reclaim sales tax on locally manufactured machinery, while firms with annual revenue below RM50mil would be exempt from the RM2,000 minimum wage requirement.
In contrast, larger labour-intensive companies, particularly plantations, manufacturers and retailers, could face margin pressure from higher wage costs and requirements to pay salaries through banks.
Yu also highlighted RM25bil earmarked for domestic investments by government-linked investment companies under the GEAR-uP programme in 2027, including data centre and semiconductor projects.
He said these investments could support domestic asset valuations, although the increasing allocation of retirement savings towards policy priorities warranted monitoring.
On sovereign ratings, Yu did not expect immediate action following the budget, with rating agencies likely to view the fiscal measures as mixed to slightly negative.
He noted that tax revenue stood at 12.8% of GDP, while debt servicing costs were projected to rise 6.5% to RM61bil, or 16% of government revenue, exceeding the Finance Ministry's 15% threshold.
Yu said the 3.3% deficit target alone was unlikely to trigger a sovereign rating upgrade, with measures to broaden the tax base likely to carry greater weight.
He added that investors should monitor demand at upcoming MGS auctions and further revenue measures to assess the government's fiscal progress.