Could 2019 be the year where Malaysians from all walks of life finally catch the break that they have been waiting for? No, if developments so far this year are any indication.
The ringgit’s continued depreciation, a less than favourable GDP growth rate projection and a soft property market outlook indicate that there could be more pitfalls and valleys to navigate in the new year.
For investors, the ongoing China-US trade tensions and depreciating emerging market currencies have stirred up a storm in global financial markets and engulfing investors in a sea of uncertainty.
The market will likely remain volatile until the issues are resolved.
Meanwhile, the strength of the US dollar against regional currencies will continue to put regional markets under pressure.
So, how should an individual investor prepare for 2019?
In order to effectively grow wealth in a volatile and uncertain environment, one must have in place an investment and wealth management strategy. Importantly, the strategy should encompass one’s own unique circumstances. In short, you’d need a guide that would help you stay focus and get back on track to reach your unique financial freedom goals amidst all the noise and distractions.
Based on my experience, there is no better way than building your own personalised roadmap to financial freedom.
Acting as a guide to your overall wealth management strategy, a well developed roadmap to financial freedom can give you insights to the following key performance indicators:
> Your optimal investment return to target
> Your optimal savings target
> Your optimal spending amount - be it your current lifestyle spending, your children’s tertiary education spending or your retirement lifestyle spending.
To illustrate my point, let me share with you how I helped Kenny developed his roadmap to financial freedom to guide his investment strategies.
Kenny is a senior manager in a multi-national corporation. Although he was only 39 when we first met, he was already earning RM360,000 in annual salary and bonuses.
However, despite Kenny’s good fortune, he has little to no savings at the end of every month. His wife is a human resources manager in a public listed company. She takes home about RM120,000 annually.
Kenny told me that he was interested to develop a savings and investment strategy plan to ensure that he can retire comfortably at 55. He is aware that he hasn’t been saving and accumulating much wealth.
Instead, he and his wife spend most of their incomes maintaining an expensive lifestyle. They use mostly branded items, live in a big and lavish, renovated bungalow and take numerous overseas vacations every year. As age caught up, Kenny was becoming more uneasy and concerned about his future. He wanted to know if there’s any impact to his finances if he continued to stay the current course.
The following fact-finding process captured Kenny’s financial details:
> He is 39 years old and his wife is 32.
> He has three children: one son aged 10 and two daughters aged nine and seven respectively.
> He earns an annual income of RM360,000.
> His wife earns an annual income of RM120,000.
> He has the following financial assets:
> House – RM1,000,000 with RM700,000 mortgage loan
> Unit trusts – RM90,000
> Bank deposits – RM100,000
> Shares – RM20,000
> EPF – RM400,000 (himself), RM150,000 (wife)
> He and his family currently spend RM160,000 per year, excluding mortgage repayment, insurance premiums and income taxes.
> They spend about RM50,000 a year on family vacations.
> He and his wife intend to retire with RM160,000 living expenses per year.
> They plan to work till age 55.
> He would like to provide RM300,000 each for their medical expenses in old age.
> They would like to provide RM200,000 each for their children’s tertiary education.
After calibrating the information, Kenny’s current roadmap to financial freedom looks like this:
Current roadmap to financial freedom
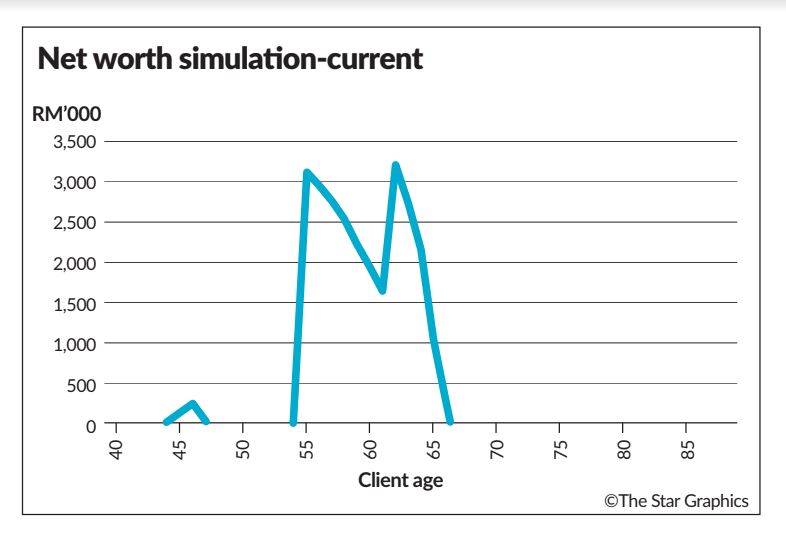
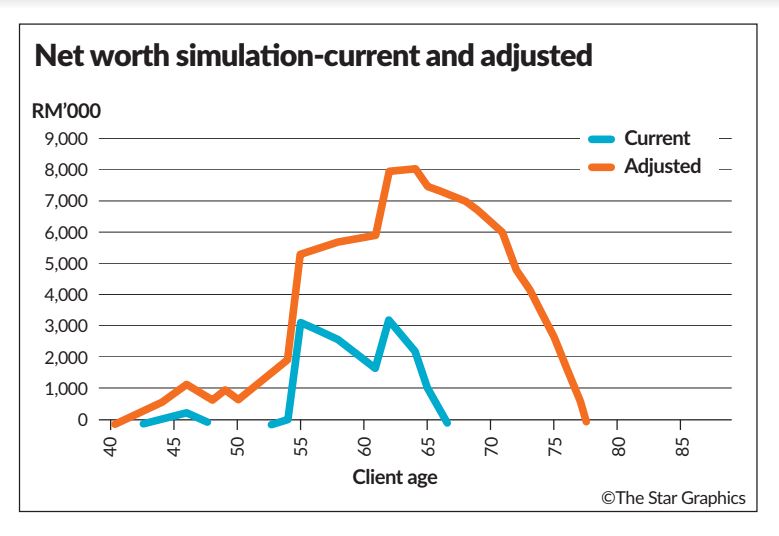
We can observe that Kenny’s net worth is in the negative from age 39 to 44, due to his total investable assets being less than his mortgage loan. In other words, Kenny is not making enough or has enough wealth to fund his loan. Nevertheless, when Kenny reaches age 44 to 47, his net worth will be positive once again. Kenny’s net worth takes another hit at the age of 48, when his eldest child enters university. It would continue to remain negative until Kenny reaches the age of 54.
At 55, Kenny‘s net worth will surge to about RM3mil when he withdraws from his EPF. But it will continue to drop until his wife withdraws her EPF, bringing their combined net worth to RM3 million. From there onwards, their combined net worth would head south, declining to zero when Kenny reaches 67 years old.
Kenny and his wife knew they weren’t in good financial shape, but they had no idea that their finances would be so atrocious.
The roadmap to financial freedom they created reaffirmed their gut instinct that they had to take action before it is too late.
It should be noted that one of Kenny’s biggest mistakes is not having the foresight nor the game plan to invest confidently.
The first adjustment that I made for Kenny and his wife was to increase their average investment portfolio ROI from 5.57% to 8%.
By doing this, their family wealth will last till age 69, which is still far from ideal.
Stress test for higher ROI at 8%
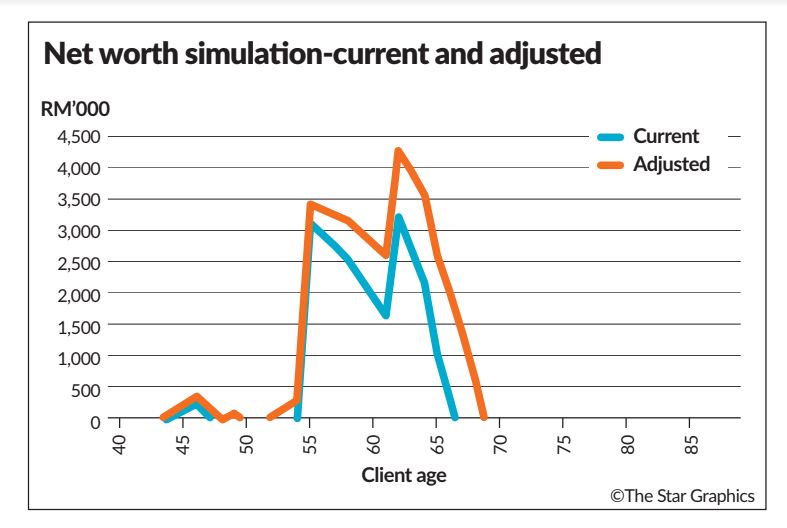
Next, I asked Kenny if he would agree to save another RM40,000 annually by reducing his current living expenses to RM120,000 per year. After the adjustment, his roadmap will look like this:
> Roadmap to financial freedom for Kenny and his family
(Stress test for extra saving of RM40,000)
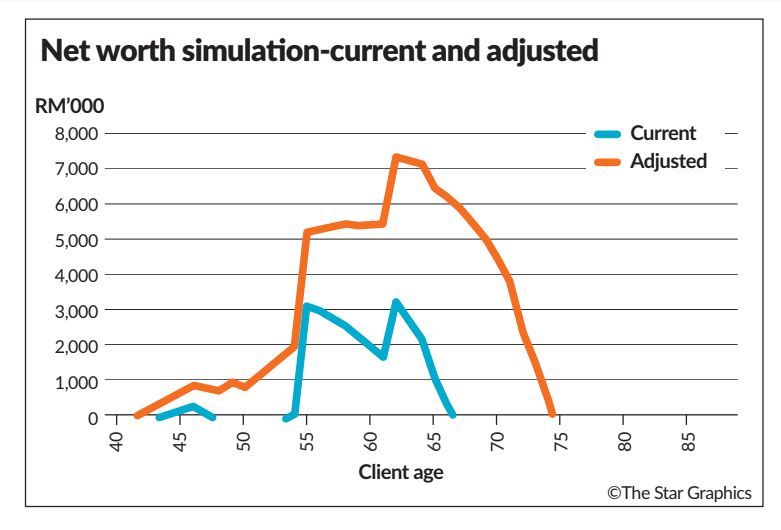
From the roadmap, we can see that Kenny’s wealth will now last till he’s 74.
However, the goal is to get his wealth to last beyond the age of 80. On a whim, Kenny’s wife suggested reducing their annual vacation budget from RM50,000 to RM30,000 annually. She believes that they can have an enjoyable holiday with a lower budget if they plan meticulously.
> Roadmap to financial freedom for Kenny and his family
(Stress test for lower vacation budget of RM30,000)
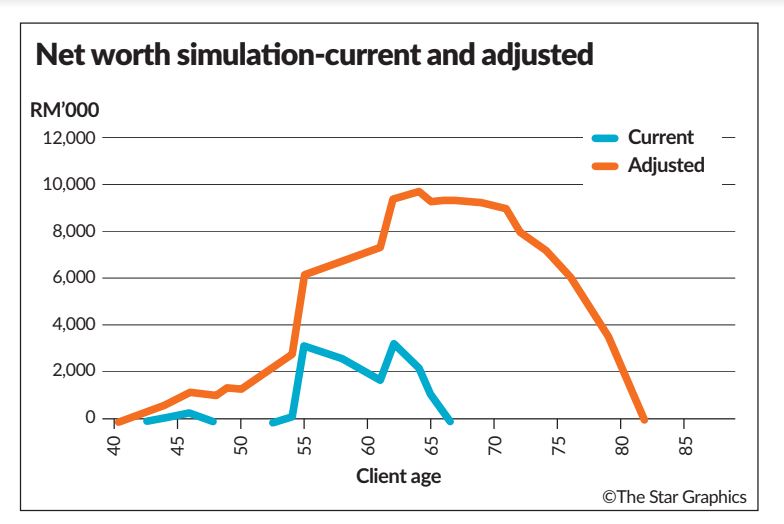
Once the roadmap incorporated a reduced vacation budget of RM30,000, we can see that Kenny’s wealth will last till he hits 81.
Although this means that Kenny and his family have achieved their goal of financial security until his 80th year, there were other positive changes that could still be made. In particular, I pointed out to Kenny that his plan to allocate RM200,000 for each child would be insufficient to fund a decent tertiary education. I suggested to increase the education funding for each child from RM200,000 to RM300,000. Kenny agreed. Therefore, his adjusted roadmap looks as follows:
> Roadmap to financial freedom for Kenny and his family
(Stress test for higher education funding)
From the adjusted roadmap, we can see that Kenny’s wealth will last until the age of 78. As a result, we needed to make one final adjustment. We reduced Kenny’s retirement living expenses from RM160,000 to RM144,000 per annum. With the new adjustment, their roadmap looks like it does below. As you can see, Kenny’s wealth will last till the age of 81.
> Roadmap to financial freedom for Kenny and his Family
(Stress test for lower retirement living expenses of RM144,000)
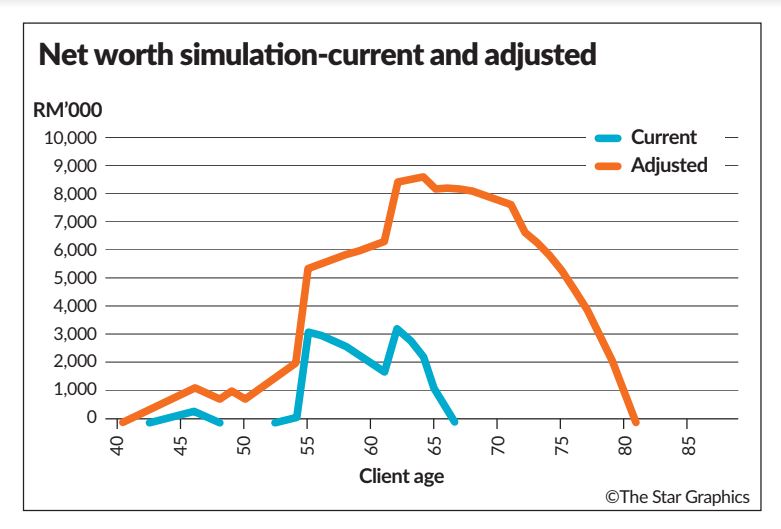
At the end of the roadmap to financial freedom exercise, Kenny and his wife have managed to produce an optimum roadmap.
Based on Kenny’s optimum roadmap to financial freedom analysis, Kenny and his wife would need to take the following actions as soon as possible:
> Restructure their existing investment portfolio from an estimated average of 5.27% ROI to 8% ROI.
> Kenny will start a new regular savings programme to save an additional RM40,000 a year.
> Kenny’s wife will plan their holidays within the annual budget of RM30,000.
> They will increase their children’s tertiary education funding from RM200,000 to RM300,000 per child.
> They will adjust their retirement living expenses from RM160,000 to RM144,000 per year.
Lessons from Kenny’s story
Thanks to the roadmap, Kenny and his wife discovered they are not saving and growing their wealth sufficiently to achieve their financial freedom.
Fortunately, the roadmap’s timely diagnosis meant that it is not too late for Kenny and his wife to start saving more during their prime earning years and ensuring that their wealth can grow steadily.
The lesson here is that financial freedom is attainable, and it does not need to cost you a lot to reach it.
By knowing exactly where to fine tune and how much adjustments is needed, Kenny and his wife discovered that they can still achieve their financial freedom without drastically changing their current lifestyle.
Now they can banish their guilt and truly enjoy their lives with complete peace of mind. By looking at their finances with a renewed perspective, Kenny and his wife is able to lead out the rest of their lives with confidence knowing that they would have enough wealth to last them into their golden years, and still afford to fulfill their responsibilities of giving their children a good education. It is not too late to start building your own roadmap to financial freedom. Hence, if you are serious about achieving your financial freedom, make sure that you take the right wealth management actions in 2019.
As Benjamin Graham, a renowned economist known as the father of value investing, puts it: “The best way to measure your investing success is not by whether you’re beating the market but by whether you’ve put in place a financial plan and a behavioral discipline that are likely to get you where you want to go.”
Already a subscriber? Log in
Get 20% OFF The Star Digital Access
Cancel anytime. Ad-free. Unlimited access with perks.